Does Homeowners Insurance Cover Water Damage in Arkansas?
Standard Arkansas homeowners insurance policies (HO-3) cover sudden and accidental water discharges—such as burst frozen pipes, ruptured water heater tanks, or washing machine hose failures—but exclude gradual leaks, maintenance neglect, rising floodwaters from outdoors, and sewer backups unless an optional endorsement is purchased.
The Core Standard: "Sudden and Accidental" vs "Gradual Seepage"
The fundamental principle governing water damage claims in Arkansas is the sudden and accidental rule. If a plumbing supply line splits overnight or a cold snap causes an attic pipe to burst, the resulting water damage to flooring, drywall, and ceilings is generally covered. Conversely, if a shower pan has been slowly dripping behind tile for six months or a toilet base has leaked into subfloor wood over years, insurers classify the loss as preventable maintenance neglect and will deny the claim.
Get Connected with a Local Contractor
Dispatch operates 24/7 across Little Rock, North Little Rock, Sherwood, Maumelle, Bryant, Benton, Conway, and Jacksonville.
What Standard Arkansas Policies (HO-3) Typically Cover
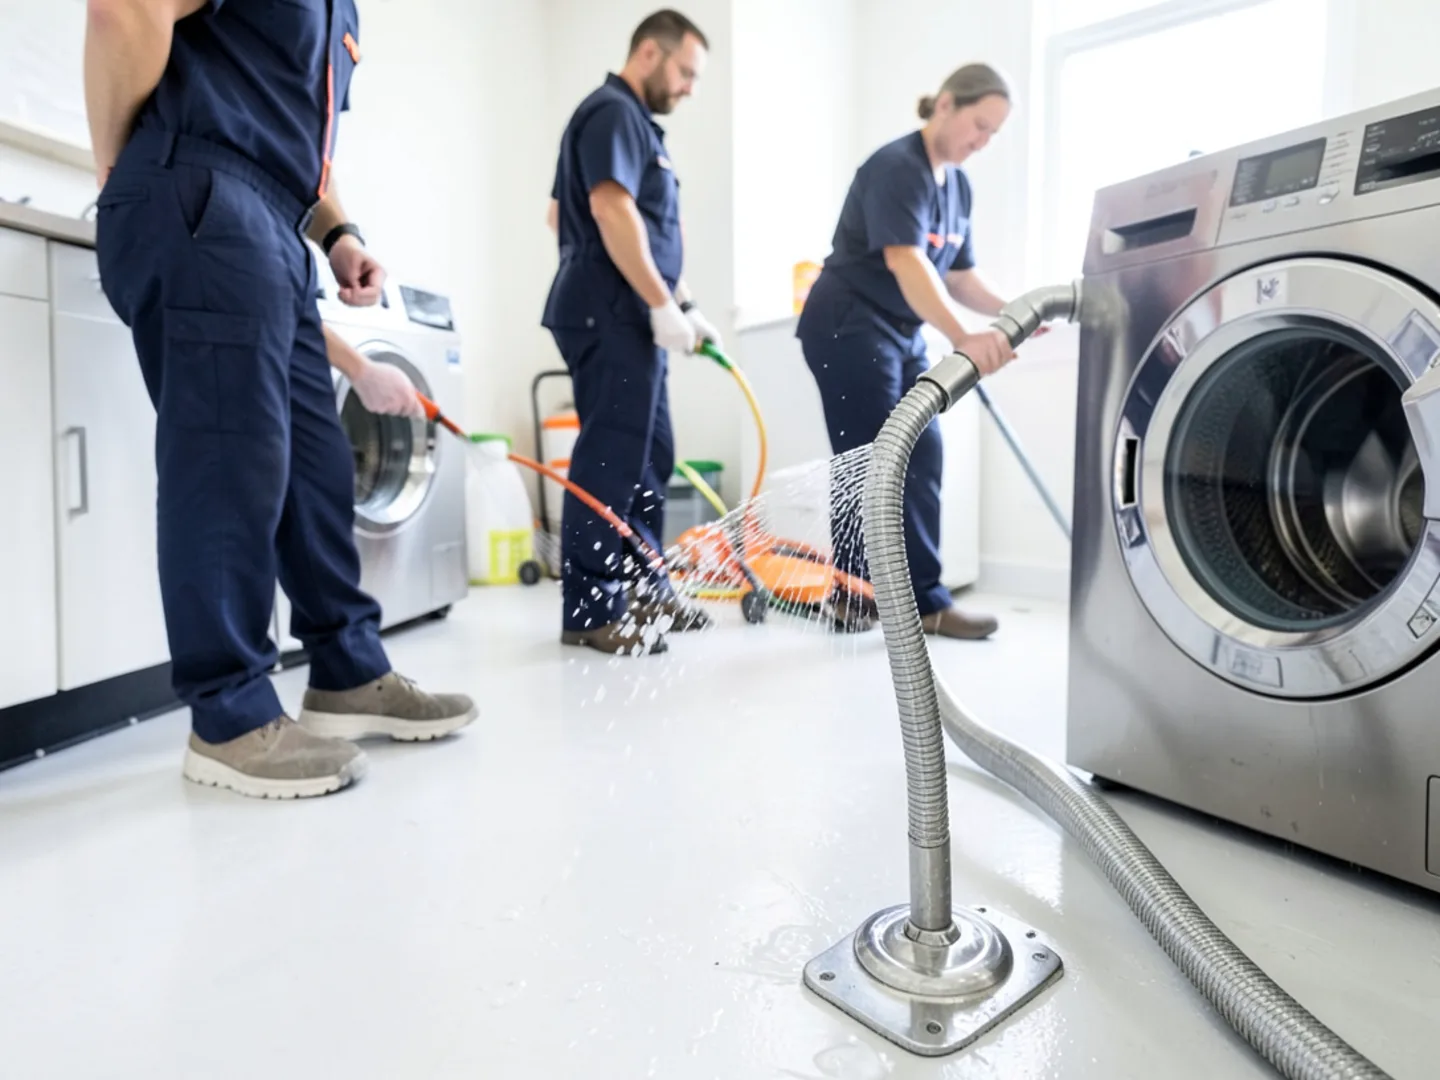
In Central Arkansas, covered water loss scenarios generally include: burst domestic water pipes caused by freezing or pressure spikes; accidental overflow of kitchen or bathroom appliances (dishwashers, washing machines); sudden water heater tank ruptures; and rainwater entering through roof punctures or broken windows caused directly by storm wind, hail, or fallen trees. Coverage typically reimburses the cost of emergency water extraction, structural dehumidification, drywall tearout, and replacing damaged flooring and trim.
Major Exclusions: River Floods, Surface Runoff, and Ground Seepage
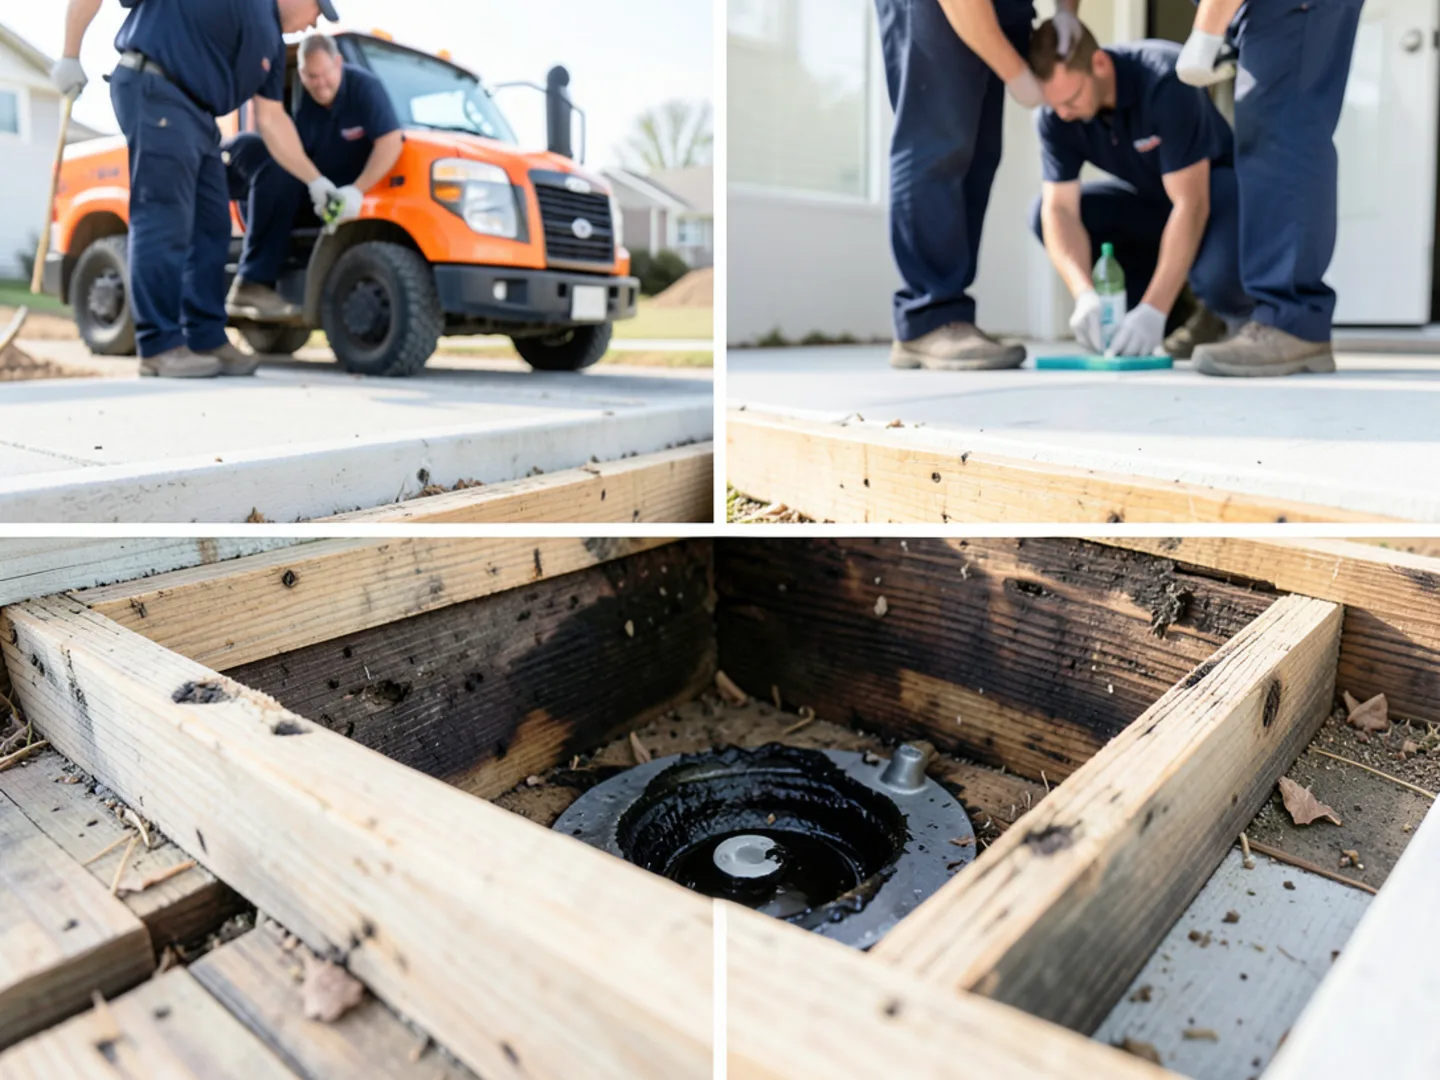
A critical distinction that catches many Little Rock homeowners off guard is the flood exclusion. Standard homeowners insurance never covers rising outdoor water, river crests (such as the Arkansas River or Saline River), or flash runoff pooling in yards and entering through exterior doorways. Coverage for rising outdoor water requires a separate policy through the National Flood Insurance Program (NFIP) or a private flood insurer. Similarly, water seeping through foundation walls or crawlspace dirt floors is typically excluded under groundwater provisions.
The Sewer and Drain Backup Endorsement: An Essential Protection
Standard homeowners insurance does not automatically cover municipal sewer backups or private lateral failures. When heavy thunderstorms overwhelm Central Arkansas collection mains and force raw sewage backward through toilets and floor drains, the resulting biohazard loss is only covered if you added an optional "Water Backup and Sump Discharge or Overflow" endorsement to your policy. Given the age of clay sewer laterals in Midtown, The Heights, and North Little Rock, this inexpensive endorsement ($50–$100 annually) is highly recommended.
Understanding Replacement Cost Value (RCV) vs Actual Cash Value (ACV)
When an insurer approves a water damage claim in Arkansas, payouts are typically distributed in two distinct checks: Actual Cash Value (ACV) and Recoverable Depreciation (to reach Replacement Cost Value, or RCV). The ACV check reflects the value of damaged drywall, flooring, or cabinetry minus depreciation based on age and wear. To claim the remaining depreciation holdback, the homeowner must complete repairs through an Arkansas-licensed contractor and submit final paid invoices proving the work was done to code. Understanding this two-step disbursement prevents panic when the initial insurance payment appears insufficient to cover full reconstruction costs.
The Role of Independent Public Adjusters vs Company Adjusters
Following a major water disaster in Little Rock, homeowners often encounter three different types of insurance representatives: company adjusters, independent adjusters hired by the insurance carrier, and licensed public adjusters hired by the homeowner. Company and independent adjusters represent the financial interests of the insurance company. If you believe your carrier is drastically undervaluing water extraction or structural drying scopes, Arkansas law permits you to hire an Arkansas Insurance Department-licensed Public Adjuster. Public adjusters work directly for you on a percentage fee basis (typically 10% to 15% of the recovered settlement) to document, negotiate, and substantiate complex property losses.
Arkansas Homeowners Insurance Water Coverage Quick Reference
| Water Loss Scenario | Covered by Standard HO-3? | Policy Requirement / Endorsement | Typical Claim Actions |
|---|---|---|---|
| Burst frozen copper pipe | Yes | Heat maintained at ≥55°F during freeze | Extract water, dry framing, replace drywall |
| Attic water heater tank split | Yes | Sudden failure, not long-term rust seep | Drain ceilings, dehumidify multi-floor area |
| Arkansas River or creek flood | No | Requires separate NFIP Flood Policy | Category 3 black water extraction & sanitizing |
| Municipal sewer lateral backup | No (unless endorsed) | Requires Water Backup Endorsement | Biohazard containment, demo, antimicrobial wash |
| Slow shower pan leak (6 months) | No | Classified as homeowner maintenance neglect | Homeowner out-of-pocket repair |
Professional Contractor Perspective
Restoration contractors in Central Arkansas routinely utilize Xactimate—the same estimating software platform employed by major property insurers like State Farm, Allstate, and Farm Bureau. When working with an emergency restoration provider, request that they separate the emergency mitigation scope (stopping active water, extraction, drying) from the repair scope (rebuilding drywall and floors). Presenting itemized drying logs and moisture readings directly accelerates claim approval with adjusters.
In accordance with our editorial standards, our informational guides and process breakdowns are grounded in verifiable documentation from state licensing boards, municipal utility codes, and official meteorological data:
- 1.Arkansas Insurance Department — Consumer Guide to Homeowners Insurance.
- 2.FEMA / National Flood Insurance Program — Policy coverage rules.
- 3.Insurance Information Institute — Water damage and freezing pipe claims data.